Australian Casino Payment Methods 2026: The Complete Speed, Fee & Withdrawal Comparison
 Available in US
PayID settled in 25 minutes. Bitcoin took 42. The Neosurf voucher deposited instantly but left the player hunting for a withdrawal method three hours later when the session turned profitable. Same casino, same evening, three radically different banking experiences.
The Australian online casino payment landscape in 2026 splits cleanly into methods that work and relics that don’t. POLi shut down in September 2023. Credit cards face a federal ban since June 2024. Major banks block debit cards selectively—Commonwealth and ING say no, NAB and Westpac say yes, all for the same MCC 7995 gambling transaction code. Meanwhile PayID became the default, cryptocurrency carved out the speed advantage, and e-wallets claimed the privacy niche.
This guide unpacks which payment methods function reliably at offshore casinos serving Australian players, what they cost, how fast they move money both directions, and which method suits your specific priorities. The Interactive Gambling Act 2001 prohibits locally-licensed online casinos, so every real-money pokies session runs through an offshore operator. That makes payment-method choice critical: you need rails that your Australian bank won’t block on the way out and that the casino actually supports on the way back.
Payment Methods for Australian Online Casino Players: The 2026 Landscape
Twenty-two payment methods currently claim Australian casino compatibility. Fourteen work reliably. Three died or face blanket blocks. Five exist in technical limbo—accepted by fewer than 15% of operators, useful as backups but not primary rails.
What Has Changed in Australian Casino Banking (2020–2026)
The credit card ban arrived June 2024 via the Interactive Gambling Amendment Act 2023. Every Australian credit card now blocks MCC 7995 gambling transactions by federal law, not bank policy. No exceptions, no workarounds. Debit cards remain legal but bank-dependent: Commonwealth Bank and ING extended the block to their debit products voluntarily, while NAB, Westpac, and ANZ still process debit gambling transactions as of 2026.
PayID scaled from niche curiosity in 2020 to default deposit method by 2023. The New Payments Platform infrastructure settles transfers in under 60 seconds, 24/7, with zero fees to end users. Offshore casinos adopted it rapidly because Australian players demanded a rail that banks wouldn’t flag or delay. By 2026, roughly 70% of Australian-facing operators accept PayID deposits, and perhaps half of those process PayID withdrawals.
Cryptocurrency matured from Bitcoin-only to multi-coin menus. Tether USDT on the Tron blockchain (TRC-20) became the preferred crypto rail for Australian players during 2024–2026, offering sub-minute settlement and fees below one Australian dollar. Bitcoin still dominates casino acceptance at 70%+ of operators, but players chasing speed and low costs shifted to USDT-TRC20 or Solana.
POLi Payments shut down permanently on 30 September 2023 after Australian Payments Plus acquired and discontinued the service. The screen-scraping model—users entering bank credentials on a third-party site—conflicted with modern banking security standards, and the NPP infrastructure made POLi redundant. Any casino listing POLi in 2026 runs outdated information or worse.
What Works vs What’s Dead in 2026
Working reliably: PayID and OSKO (instant bank transfer via NPP). Bitcoin, Ethereum, Litecoin, Tether, Bitcoin Cash, Solana (crypto, varying speeds). Skrill, Neteller, PayPal, ecoPayz/Payz, MiFinity (e-wallets). Neosurf, Paysafecard, CashtoCode (prepaid vouchers, deposit-only). Visa and Mastercard debit cards (bank-dependent, NAB/Westpac/ANZ generally allow). BPAY (legacy bill-payment rail, 1–2 day settlement). Trustly (international instant bank transfer, limited Australian casino acceptance). Traditional bank transfer via BSB and account number (slow but high limits).
Dead or blocked: POLi (shut down September 2023). All credit cards (federal ban since June 2024). Commonwealth Bank and ING debit cards (voluntary bank block on gambling MCC).
Technical limbo: Apple Pay and Google Pay (accepted at under 15% of Australian-facing casinos, subject to same bank blocks as underlying cards, no advantage over direct card use or PayID). American Express (premium card network, roughly 30% casino acceptance versus 80% for Visa/Mastercard, higher merchant fees drive lower adoption, credit ban applies, debit Amex rare in Australian market).
Do online casino payments appear on my bank statement?
Yes, with variation by method. PayID, debit cards, BPAY, and traditional bank transfers all create Australian bank statement entries. The descriptor depends on the casino’s payment processor—sometimes a recognizable casino name, often a generic merchant descriptor like “Online Services” or a processor company name. The transaction itself is visible; what shows as the payee varies.
E-wallets (Skrill, Neteller, PayPal, ecoPayz, MiFinity) create two-stage entries. Your bank statement shows the transfer to the e-wallet provider (e.g., “Skrill Limited”), not the casino. The casino transaction happens inside the e-wallet and doesn’t touch your bank statement. Withdrawals appear as transfers from the e-wallet back to your bank.
Prepaid vouchers purchased with cash leave no bank record at all. Vouchers bought with a card show the retailer or voucher issuer (e.g., “Neosurf”) under merchant category code 5947 (prepaid cards/gift cards), not 7995 (gambling). The casino redemption doesn’t appear on your bank statement because the voucher is the payment instrument, not your bank account.
Cryptocurrency transactions bypass the banking system entirely until you convert back to Australian dollars. Moving AUD to a crypto exchange shows as a transfer to the exchange (e.g., “CoinSpot”). Casino deposits and withdrawals happen blockchain-to-blockchain with no bank statement trace. Converting crypto winnings back to AUD creates a second bank entry showing the exchange as the sender. AUSTRAC requires exchanges to report fiat conversions over $10,000 under AML/CTF Act provisions, but the casino itself never appears in your banking records.
| Method | Deposit Speed | Withdrawal Speed | Typical Fees | Best Use Case |
|---|---|---|---|---|
| PayID | Instant (<1 min) | 1–4 hours | Zero | Default choice: instant, free, bi-directional |
| USDT (TRC-20) | <1 min | <1 hour | <$1 network fee | Speed priority, privacy, volatility avoidance |
| Bitcoin | 10–60 min | 10–60 min | $1–5 network fee | Maximum casino choice, crypto-comfortable |
| Skrill | Instant | 24 hours | 1–2% AUD conversion | Privacy, bonus-eligible at some casinos |
| Neteller | Instant | 24 hours | 1–2% AUD conversion | Privacy, interchangeable with Skrill |
| PayPal | Instant | 24–72 hours | Zero (typically) | Trust, limited casino acceptance (~10%) |
| ecoPayz | Instant | 24 hours | 1.5–2% AUD conversion | Gambling-focused, tiered accounts |
| MiFinity | Instant | 24 hours | 1–2% AUD conversion | Skrill alternative, eVoucher hybrid option |
| Neosurf | 2–15 min | N/A (deposit-only) | 3.5–15% purchase fee | Cash option, hard budget cap, privacy |
| Paysafecard | 2–15 min | N/A (deposit-only) | 4–10% purchase fee | International brand, less AU distribution |
| CashtoCode | 2–15 min | N/A (deposit-only) | ~5% fee | Cash-to-barcode, niche acceptance |
| Visa Debit | Instant | 2–5 business days | 1–3% at many casinos | Familiar, bank-dependent (NAB/Westpac/ANZ) |
| Mastercard Debit | Instant | 2–5 business days | 1–3% at many casinos | Familiar, bank-dependent (NAB/Westpac/ANZ) |
| Amex | Instant | 2–5 business days | 3–5% at many casinos | Premium positioning, 30% casino acceptance |
| Ethereum | 1–5 min | 1–5 min | $1–8 gas fee | Faster than Bitcoin, ERC-20 token support |
| Litecoin | 2–10 min | 2–10 min | <$0.10 fee | Low fees, faster than Bitcoin |
| Bitcoin Cash | 10–30 min | 10–30 min | $0.10–1 fee | Bitcoin alternative, niche |
| Solana | <1 min | <1 min | <$0.01 fee | Fastest/cheapest crypto, growing acceptance |
| BPAY | 1–2 business days | Rare | Zero | High limits, familiar to older Australians |
| POLi | N/A | N/A | N/A | Shut down September 2023 — do not use |
| Trustly | Instant | Instant | Zero (user) | International instant transfer, <10% AU acceptance |
| Apple Pay | Instant | Rare | Same as underlying card | iOS convenience, <15% acceptance, bank blocks apply |
| Google Pay | Instant | Rare | Same as underlying card | Android convenience, <15% acceptance, bank blocks apply |
The table surfaces the split between instant-deposit rails (PayID, crypto, cards, e-wallets) and legacy batch-settlement systems (BPAY, traditional bank transfer). Withdrawal speed separates further: crypto and PayID at the top end (minutes to hours), e-wallets in the middle (24 hours typical), cards and bank transfers at the slow end (days). Vouchers sit outside the withdrawal column entirely—they’re one-way only, forcing players to nominate a second method when cashing out.
PayID and OSKO: Australia’s Native Casino Banking Standard
PayID became the Australian online casino deposit standard because it solved three problems simultaneously: instant settlement without card-network merchant fees, bank-verified identity reducing fraud, and zero cost to end users. The infrastructure sits on the New Payments Platform, managed by Australian Payments Plus and backed by every major Australian bank. Launch happened February 2018 for person-to-person transfers. Casinos adopted it gradually, then rapidly once credit cards faced blocks and POLi died.
The mechanism links a mobile number, email address, or ABN to a BSB and account number. You register a PayID inside your banking app, nominating which account receives payments sent to that identifier. When depositing at a casino, the cashier generates a unique reference code. You open your bank app, initiate a PayID transfer to the casino’s registered PayID (usually a mobile number displayed in the cashier), enter the reference code in the payment description field, send. The casino’s system matches the reference code to your account and credits the balance, typically within 30–90 seconds.
OSKO is the consumer-facing brand for instant NPP payments. Functionally, PayID and OSKO refer to the same infrastructure—real-time settlement on the New Payments Platform. Banks display “Pay with OSKO” or “PayID transfer” depending on their app design, but the underlying rail is identical. Settlement happens 24/7 including weekends and public holidays, with Confirmation of Payee displaying the recipient’s registered name before you authorize the transfer.
How PayID Works at Online Casinos
Casino cashiers display a deposit flow: select PayID, enter your desired deposit amount (minimum typically $10–20), receive a unique reference code and the casino’s PayID identifier. Some operators display a QR code encoding both values. You switch to your banking app, select the PayID or OSKO transfer option, enter the casino’s PayID as recipient, input your deposit amount, paste or type the reference code into the description or reference field (this step is critical—omitting the reference code means manual processing delays), authenticate with your usual bank security (PIN, fingerprint, Face ID), confirm.
The casino’s system polls for incoming NPP transactions matching generated reference codes. When your transfer arrives—usually within 60 seconds—the system credits your casino balance and displays confirmation. Total time from clicking deposit to seeing credited funds: one to three minutes for the entire round trip.
PayID Deposit Process
First-time PayID deposits trigger an account name verification. The casino compares the sender name on the NPP transaction (transmitted as part of the Confirmation of Payee data) against the name on your casino account. Mismatches block the deposit and require customer support intervention. This anti-money-laundering measure means the bank account sending PayID funds must match your registered casino account name. Using a spouse’s or friend’s account to deposit will fail.
Subsequent deposits after the first skip this verification—your bank account is marked as validated. The reference code remains mandatory on every transaction. Deposits sent without a reference code or with a mistyped code end up in the casino’s suspense account, requiring you to email customer support with transaction details. Manual matching can take two hours to two days depending on the operator’s support volume.
PayID Withdrawal Times and Limits
PayID withdrawals vary dramatically by operator. Hell Spin processed a test withdrawal in 25 minutes total (from withdrawal request to funds in bank account). Goldenbet took 28 minutes. Lucky7 completed the round trip in 35 minutes. These are genuine “instant” withdrawals—operator processing plus NPP settlement both measured in minutes, not marketing promises followed by 24-hour holds.
Other operators quote “same day” or “under 4 hours” but process in batch cycles. Wintino’s PayID withdrawals consistently take 2–3 hours according to tested data, five times slower than Hell Spin on identical infrastructure. The difference is internal: fast operators run automated approval for verified accounts under certain thresholds (often $5,000–10,000), while batch processors hold withdrawals for manual review or fixed payout windows.
First withdrawals always take longer due to Know Your Customer verification. Expect document upload requests (photo ID, proof of address, sometimes a bank statement showing your account details to verify PayID ownership) and processing delays of 12–72 hours while the compliance team reviews. Upload documents immediately when registering rather than waiting until you request your first withdrawal—this cuts two days off the first cashout.
Bank-by-Bank PayID Limits and Uplift Options
Default daily PayID transfer limits vary by bank. ING sets the lowest at $1,000 per day. Bendigo Bank and Bank of Queensland default to $10,000. Westpac allows $20,000. NAB and ANZ permit $25,000. These limits apply to total outbound PayID transfers per rolling 24-hour period, not per transaction. A $25,000 casino deposit on a NAB account exhausts your daily limit; a second deposit attempt that day fails until the 24-hour window rolls over.
Most banks offer in-app limit increases. Commonwealth Bank allows uplift to $50,000 via the CommBank app under security settings. NAB uplifts to $40,000. Westpac reaches $50,000. ANZ varies by account type. The uplift process typically requires additional authentication (confirming via SMS code or NetCode token) and takes effect immediately or within minutes.
Some banks impose lower PayID limits specifically on accounts flagged for gambling activity. Commonwealth Bank’s fraud-monitoring algorithms profile repeat offshore gambling transfers and may reduce limits or impose transaction holds without explicit notice. This bank-side friction sits outside the casino’s control. Players encountering persistent PayID failures despite being under stated limits should contact their bank directly—often the account has been soft-blocked pending fraud review.
| Bank | Default Daily Limit | Uplift Limit | Uplift Method | Notes on Gambling Blocks |
|---|---|---|---|---|
| Commonwealth Bank | $10,000 | $50,000 | CommBank app security settings | Aggressive fraud profiling; frequent gambling may trigger review |
| NAB | $25,000 | $40,000 | NAB app payment settings | Generally gambling-neutral; allows debit cards |
| Westpac | $20,000 | $50,000 | Westpac app transfer limits | Allows debit gambling; offers voluntary gambling block feature |
| ANZ | $25,000 | Varies by account | ANZ app or branch | Allows debit gambling; limit uplift requires phone/branch for some accounts |
| ING | $1,000 | $5,000 | ING app settings | Blocks debit cards for gambling MCC; PayID works but low limits |
| Bendigo Bank | $10,000 | $30,000 | Online banking or branch | Regional bank, generally neutral on gambling |
| Bank of Queensland | $10,000 | $30,000 | BOQ app or phone banking | Neutral stance; limit uplifts processed quickly |
| ubank | $5,000 | $20,000 | ubank app | NAB-owned neobank; gambling-neutral |
| Up | $5,000 | $10,000 | Up app settings | Bendigo-backed neobank; lower limits due to neobank risk profile |
The table shows Commonwealth Bank’s $10,000 default looks mid-range but sits below NAB/ANZ, and ING’s $1,000 limit makes it impractical for anything beyond micro-stakes sessions. For players running larger bankrolls, NAB and ANZ offer the highest default limits with straightforward uplift paths. Westpac balances access and limit flexibility.
The Reference Number Mistake That Delays Deposits
The single most common PayID deposit error: sending the transfer without the reference code in the description field. The casino’s automated crediting system matches incoming NPP transactions to pending deposits via that unique reference. No reference, no match, no automatic credit. Your money lands in the operator’s master account but sits unallocated.
Resolution requires emailing customer support with your transaction screenshot showing the sender name, amount, timestamp, and transaction ID. Support manually matches your transfer and credits your account. Best-case resolution time: 30 minutes during peak support hours. Worst-case: 48 hours if you sent the deposit Friday night and support doesn’t staff weekends. The deposit itself is never lost—your bank statement proves you sent it—but you can’t play until the manual matching completes.
Some banking apps auto-fill the description field with saved payee notes or clear it after each transaction. Double-check the reference code is present before authorizing the transfer. Copy-paste from the casino cashier rather than typing manually—a single wrong digit produces the same mismatch as omitting it entirely.
What’s the difference between PayID and OSKO?
PayID is the addressing layer (linking your mobile number or email to your account), and OSKO is the payment service brand. Both refer to the New Payments Platform infrastructure. When you send money via “PayID,” you’re using OSKO’s instant settlement. When you send via “OSKO,” you’re using PayID addressing or BSB/account number addressing. Functionally identical from the user’s perspective—real-time settlement, Confirmation of Payee, zero fees, 24/7 availability.
Banks brand the feature differently in their apps. Commonwealth Bank calls it “PayID” in the interface. NAB shows “PayID and Pay Anyone” as menu options. Westpac displays “OSKO” as a tag on instant transfers. ANZ uses “Pay with PayID.” All four banks, all using the same underlying NPP rail, all settling in under 60 seconds. The branding split causes confusion but doesn’t change how the system functions or which casinos accept it.
Is PayID safe to use at online casinos?
Yes, with caveats around the same risks any bank transfer carries: you’re sending money to an offshore entity, and chargebacks don’t exist on NPP transfers. Once you authorize a PayID payment, it’s final. Unlike credit cards, which offer dispute and chargeback mechanisms, PayID transactions are irrevocable. If you deposit to a scam site, your bank cannot reverse the transfer.
The safety comes from the infrastructure itself—NPP is bank-grade encrypted, Confirmation of Payee prevents sending to mistyped or fraudulent identifiers, and the transaction doesn’t expose your card number or broader banking credentials. What PayID doesn’t protect you from is depositing to an unlicensed or non-paying casino. Stick to operators holding Curaçao, Malta, or other recognized offshore licenses, with track records of processing withdrawals. PayID as a payment rail is secure; the operator you’re sending to requires the same due diligence any offshore transaction demands.
Bank statement visibility is a secondary consideration. PayID transfers show the recipient name or payment descriptor on your statement, not a generic “transfer” entry. If you’re using a shared bank account or prefer not to show casino transactions, PayID’s transparency is a drawback compared to vouchers or crypto. For solo accounts, it’s a non-issue.
Credit and Debit Cards: Visa, Mastercard, and Amex
The Interactive Gambling Amendment (Credit and Other Measures) Act 2023 banned credit cards for online wagering effective 11 June 2024. Every Australian credit card now blocks merchant category code 7995 (gambling transactions) at the network level. Visa, Mastercard, American Express—all uniformly blocked. The law targets credit and credit-related products, which includes buy-now-pay-later services, credit card cash advances, and overdraft facilities. No exceptions, no offshore workarounds. Attempting a credit card deposit at an online casino returns an immediate decline.
Debit cards remain legal but bank-dependent. Commonwealth Bank extended the gambling block to its debit cards voluntarily, ahead of any regulatory requirement. ING followed. NAB, Westpac, and ANZ continue processing gambling transactions on debit Visa and Mastercard as of 2026, treating them as ordinary purchases. The result: whether your debit card works at an online casino depends on who issued it, not what the law says.
Card deposits, when they work, settle instantly. You enter card number, expiry, CVV, authorize, funds appear in your casino balance within seconds. Withdrawals reverse the flow, returning funds to the same card used for deposit under card network rules. Timeline: two to five business days for the refund to post to your account. Many offshore operators charge a processing fee for card deposits—one to three percent is typical—where PayID and crypto cost nothing.
American Express occupies a smaller niche. Amex’s closed-loop network (the company is both card issuer and network operator, unlike Visa and Mastercard’s open-loop model) results in higher merchant fees. Offshore casinos pay 2.5–3.5% on Amex transactions versus 1.5–2.5% for Visa and Mastercard. That cost difference drives acceptance: roughly 30% of Australian-facing casinos accept Amex compared to 80% for Visa and Mastercard. The credit ban applies equally to Amex; debit Amex products are rare in the Australian market, leaving American Express mostly inoperable for casino deposits in 2026.
Can I use my credit card to deposit at an online casino in Australia?
No. Federal law banned credit cards for online gambling effective June 2024. The ban is absolute—applies to every Australian-issued credit card regardless of the bank, applies to all online wagering including casinos and sportsbooks, applies to offshore operators even though they don’t hold Australian licenses. The mechanism is merchant category code screening: when you attempt a deposit, your card network identifies the merchant as MCC 7995 (gambling), applies the federal block, returns a decline. The transaction never reaches the casino’s payment processor.
Some players attempt workarounds—using a credit card issued by an overseas bank, or depositing via a payment processor that misrepresents the merchant category. The first is legal but impractical for most (requires overseas residency or specialized offshore banking relationships). The second violates the spirit of the law and carries risk: if the true merchant category is later identified, you’re left with a cash advance on a credit card used for gambling, potentially triggering breach of the card’s terms and making any dispute resolution complicated.
The straightforward answer: credit cards no longer function for Australian online casino deposits. Use PayID, crypto, e-wallets, or debit cards from banks that allow gambling transactions.
Do Australian banks block casino deposits and withdrawals?
Yes, selectively. Credit cards face a blanket federal ban. Debit cards split by bank policy. Commonwealth Bank blocks gambling MCC on both credit and debit cards—deposit attempts decline automatically. ING applies the same policy. NAB, Westpac, and ANZ allow debit card gambling transactions as of 2026, though all three offer voluntary gambling-block features customers can enable in their banking apps.
The block operates at the transaction level via merchant category codes. When you attempt a card deposit, your bank’s payment gateway reads the merchant category code transmitted by the casino’s payment processor. MCC 7995 identifies gambling merchants. CBA and ING decline any transaction carrying that code on debit cards. NAB, Westpac, and ANZ process it normally unless you’ve enabled the voluntary block.
PayID blocks are softer and less systematic. Banks don’t block PayID gambling transfers as a blanket policy, but fraud-monitoring systems may flag accounts showing frequent offshore gambling patterns. Commonwealth Bank is the most aggressive, occasionally imposing transaction holds or reducing limits on accounts with heavy casino activity. NAB and Westpac take a more neutral stance. The holds aren’t permanent blocks—they’re fraud-review triggers requiring you to confirm the transactions are legitimate—but they interrupt play and cause frustration.
Withdrawals face less friction. Card refunds process through the same network that accepted the deposit, so if your debit card deposited successfully, the withdrawal refund flows back without additional screening. PayID withdrawals from casinos to your Australian bank account are simply incoming NPP transfers—your bank sees money arriving, not gambling context, and processes it as any other inbound transfer. The exception: very large or very frequent casino-to-bank transfers may trigger AUSTRAC reporting thresholds or bank anti-money-laundering reviews, but that’s a volume issue, not a gambling-specific block.
Practical guidance: if you bank with CBA or ING, debit cards won’t work for casino deposits—switch to PayID, crypto, or e-wallets, or maintain a second account at NAB, Westpac, or ANZ specifically for gambling transactions. If you’re with NAB, Westpac, or ANZ and your debit card still fails, check your app settings for voluntary gambling blocks you may have enabled previously.
E-Wallets: Skrill, Neteller, PayPal, and Alternatives
E-wallets insert an intermediary layer between your bank and the casino. You fund the e-wallet via bank transfer or card, the e-wallet holds your balance, you transfer from e-wallet to casino. Withdrawals reverse the flow: casino to e-wallet, then e-wallet to your bank. The casino never sees your bank account details or card number, and your bank statement shows transactions with Skrill or Neteller, not offshore gambling operators.
Five e-wallets dominate the Australian casino market: Skrill and Neteller (sister companies under Paysafe Group, 60% combined acceptance), PayPal (10% acceptance but highest brand trust), ecoPayz/Payz (30% acceptance, gambling-focused), and MiFinity (25% acceptance, newest major player). All are UK Financial Conduct Authority regulated e-money institutions. All charge currency conversion fees for Australian dollar transactions—typically one to two percent—because they operate in euros, pounds, or US dollars and convert your AUD on both ends.
Skrill
Skrill Limited operates under Paysafe Group ownership, headquartered in the UK, regulated by the Financial Conduct Authority as an e-money institution since 2011. The service launched in 2001 as Moneybookers, rebranded to Skrill in 2011, and was acquired by Paysafe in 2015. It processes over 40 million transactions annually across gambling, e-commerce, and peer-to-peer payments.
Australian casino acceptance sits around 60% as of 2026—highest of any e-wallet except its sister company Neteller. Deposits are instant: you select Skrill in the casino cashier, log into your Skrill account, authorize the transaction, funds appear in your casino balance within seconds. Withdrawals typically complete within 24 hours once the casino processes the payout. Skrill holds the funds in your e-wallet, then you transfer to your Australian bank account (one to three business days for the bank leg).
Fees hit on currency conversion. Skrill converts AUD to EUR or USD when you fund your wallet, applies a 1–2% markup over the mid-market exchange rate, then converts back when you withdraw to your Australian bank. A round trip (AUD to Skrill to casino to Skrill to AUD) costs roughly 2–4% in total conversion fees depending on the day’s rate. Skrill charges no transaction fees for casino deposits or withdrawals—the markup is buried in the exchange rate.
Bonus eligibility is the catch. Many casinos exclude Skrill deposits from welcome bonuses and reload promotions as an anti-abuse measure. The industry observed that bonus hunters would cycle money through low-wagering games using e-wallets to extract bonuses with minimal risk. Operators responded by excluding Skrill (and often Neteller) from bonus terms. Before depositing with Skrill to claim a promotion, read the bonus terms—phrases like “deposits via Skrill, Neteller, or other e-wallets do not qualify” are common.
Neteller
Neteller predates Skrill (launched 1999 versus 2001) but shares the same parent company, technical infrastructure, and market positioning. Paysafe Group acquired Neteller in 2015, the same year it acquired Skrill, and now operates both as parallel services. Neteller holds FCA e-money institution authorization, processes payments in 200+ countries, and maintains particularly strong presence in the online gambling sector.
For Australian casino players, Neteller and Skrill are functionally interchangeable. Near-identical acceptance rates (Neteller marginally higher at some older casino brands due to its longer history), same fee structure (1–2% AUD conversion), same instant deposits and 24-hour withdrawal timing, same bonus-exclusion treatment at most casinos. The choice between them comes down to minor interface preferences or which one you already use for other purposes.
Neteller offers one distinguishing feature: the Net+ prepaid Mastercard. Link this physical card to your Neteller balance, then use it for ATM withdrawals or purchases wherever Mastercard is accepted. The card costs a small issuance fee and carries its own transaction charges, but it provides a spending option that doesn’t require transferring funds back to your bank. For players who prefer keeping gambling funds separate from their primary bank account, Net+ extends that separation into everyday spending.
The combined market share of Skrill and Neteller dominates e-wallet gambling volume in Australia. Together they account for the majority of e-wallet casino transactions, driven by their early entry into the gambling market, regulatory compliance, and near-universal operator acceptance.
PayPal
PayPal Holdings operates as the largest digital wallet globally, processing hundreds of billions in annual transaction volume. Australian operations launched in the early 2000s, with PayPal becoming ubiquitous for e-commerce by the 2010s. Brand recognition towers over competitors—most Australians have used PayPal at some point, and trust in the platform runs higher than newer entrants like MiFinity or ecoPayz.
Casino acceptance is the inverse of that trust: only around 10% of Australian-facing offshore casinos accept PayPal. The gap stems from PayPal’s restrictive merchant policies on gambling. PayPal requires gambling merchants to hold licenses from a short list of approved jurisdictions—primarily UK Gambling Commission, Malta Gaming Authority, or equivalent Tier-1 regulators. Most offshore casinos serving Australians operate under Curaçao licenses, which PayPal doesn’t accept. The result: only larger, more established casino brands with Malta or UK licenses can obtain PayPal merchant accounts.
When available, PayPal deposits are instant and typically fee-free for AUD transactions—PayPal absorbs the merchant fee rather than passing it to the customer. Withdrawals take 24 hours to three days depending on the operator’s processing cycle. PayPal’s buyer protection policies offer more recourse than Skrill or Neteller if a genuine payment dispute arises, though gambling transactions sit in a gray area and may not qualify for protection.
For Australian players, PayPal’s limited casino acceptance makes it a secondary option. If a casino accepts it, the combination of zero fees, high trust, and strong buyer protections makes PayPal attractive. But the 10% acceptance rate means you’ll need an alternative method for the other 90% of casinos.
ecoPayz
PSI-Pay Limited operates ecoPayz (rebranded to “Payz” in 2022, though the ecoPayz name persists across many casino cashiers). The company holds FCA e-money institution authorization and positions itself explicitly toward the gambling market—its marketing, partnerships, and product features all target casino and sportsbook customers rather than general e-commerce.
Four account tiers (Classic, Silver, Gold, Platinum) offer progressively lower fees as your transaction volume increases. Classic accounts pay the highest currency-conversion markups (around 2% on AUD). Platinum accounts, earned through high volume, drop fees below 1%. The tier system rewards frequent users and high rollers while remaining accessible to casual players at the Classic level.
Acceptance at Australian-facing casinos grew significantly from 2020 to 2026, rising from roughly 15% to over 30%. The increase tracks ecoPayz’s aggressive casino-partnership strategy and its willingness to work with Curaçao-licensed operators that PayPal rejects. Deposits are instant, withdrawals process within 24 hours, and the service offers an ecoVirtualcard (virtual prepaid card for online purchases) tied to your ecoPayz balance.
The gambling focus is both strength and limitation. EcoPayz is well-integrated into casino cashiers and widely recognized among players, but it lacks the mainstream brand recognition of PayPal or the e-commerce versatility of Skrill. You fund ecoPayz to gamble, not to shop on eBay or split a dinner bill.
MiFinity
MiFinity Limited is the newest of the five major e-wallets, launched in 2015 and gaining substantial Australian market share during 2020–2026. FCA-regulated like its competitors, MiFinity differentiated itself by positioning as the Skrill/Neteller alternative—lower fees in some cases, faster casino integrations, and aggressive operator partnerships that drove acceptance to roughly 25% of Australian-facing casinos by 2026.
The MiFinity eVoucher system is its distinguishing feature. Instead of funding your MiFinity e-wallet directly via bank transfer, you can purchase a MiFinity eVoucher using cash at participating retailers or via alternative payment methods. The eVoucher generates a code you redeem in your MiFinity account, which then holds the balance for casino transactions. This adds a privacy layer—your bank never sees a transfer to MiFinity, and the retailer transaction shows as a prepaid purchase, not gambling.
Fees run 1–2% on AUD conversion, matching Skrill and Neteller. Deposits instant, withdrawals within 24 hours. MiFinity also offers a prepaid Mastercard linked to your account balance. Bonus eligibility varies by casino—some exclude MiFinity from promotions like they do Skrill, others treat it as bonus-eligible.
For Australian players, MiFinity functions as a viable Skrill alternative. Comparable acceptance, similar fee structure, slightly newer platform. The eVoucher hybrid model appeals to players wanting cash-like privacy without committing to pure voucher systems like Neosurf (which are deposit-only and carry higher fees).
Prepaid Vouchers: Neosurf, Paysafecard, and CashtoCode
Prepaid vouchers work like gift cards: buy a fixed-value voucher at a retailer, receive a PIN code, redeem the code at a casino cashier. No bank account required for the purchase if you pay cash. No casino transaction on your bank statement even if you buy the voucher with a card—the retailer purchase shows as a prepaid product under MCC 5947 (gift cards), not MCC 7995 (gambling).
Three vouchers hold meaningful Australian market share: Neosurf (50%+ casino acceptance, widest retail distribution), Paysafecard (30% acceptance, international brand), and CashtoCode (under 20% acceptance, niche). All are deposit-only—you can load money into a casino with a voucher, but you cannot withdraw to a voucher. Cashouts require nominating an alternative method: bank transfer, crypto, or e-wallet.
The privacy benefit is real but comes with trade-offs. Vouchers cost 3.5–15% in purchase fees, significantly higher than PayID (zero) or crypto (under $5 network fee). Redemption at casinos takes two to fifteen minutes. Withdrawal KYC is stricter for voucher-only depositors because the casino has no bank-verified identity at deposit time—expect more rigorous document checks when you request your first cashout.
Neosurf
Neosurf Cards SAS operates from France under ACPR regulation (Autorité de contrôle prudentiel et de résolution, the French financial regulator). The company launched in 2004, expanded to Australia around 2015, and built the largest prepaid-voucher retail network in the country through partnerships with Coles supermarkets, 7-Eleven stores, Australia Post outlets, and independent newsagents.
Face values run $10, $20, $30, $50, and $100. Purchase fees vary by denomination, structured to heavily favor larger vouchers: a $100 Neosurf costs roughly $103.50 (3.5% fee), while a $10 voucher costs around $11.50 (15% fee). The fee schedule incentivizes buying the largest voucher your session budget allows, but buying more than you need leaves unused balance sitting on the voucher (subject to a 12-month dormancy fee that eats into the remaining value).
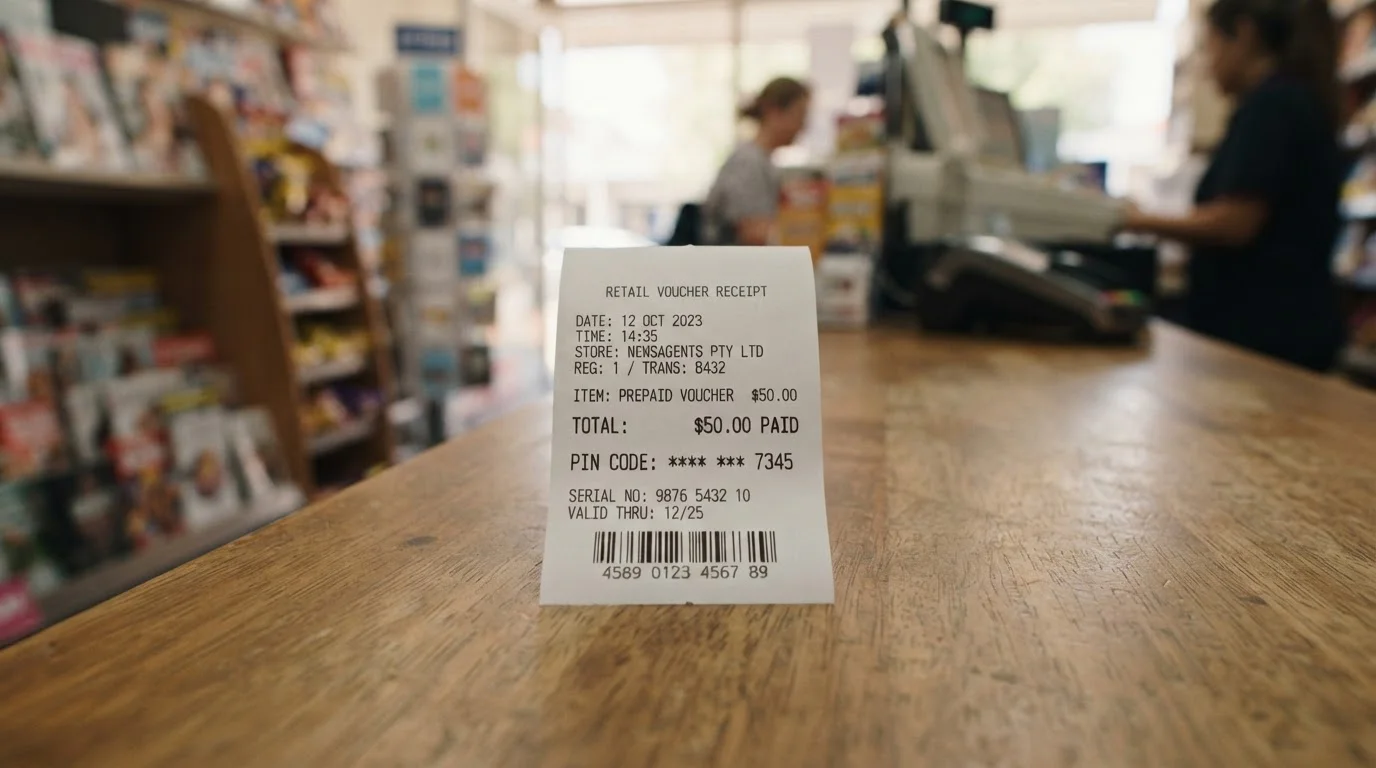
The purchase process is straightforward. Walk into Coles, ask for a Neosurf voucher at the service desk or checkout, specify the denomination, pay cash or card, receive a printed receipt with a 10-digit PIN. The receipt also displays a barcode for mobile redemption. At the casino, select Neosurf in the deposit options, enter your desired deposit amount (can be less than the voucher’s full value—partial redemption is supported), enter the 10-digit PIN, confirm. The casino debits your specified amount from the voucher balance and credits your account, typically within 2–15 minutes.
Unused voucher balance persists for future deposits. A $100 voucher can be split across five $20 deposits at different casinos or sessions. The 12-month dormancy fee kicks in if you don’t use the voucher at all during that period—Neosurf begins charging monthly maintenance fees that erode the balance. Active use resets the dormancy clock.
Casino acceptance sits above 50% of Australian-facing operators as of 2026, making Neosurf the most widely accepted voucher. The combination of retail availability (Coles’ national footprint is unmatched), established brand recognition in the gambling community, and broad casino support gives Neosurf a dominant position in the prepaid-voucher niche.
Are Neosurf vouchers worth the purchase fee?
Depends on what you’re paying for. If you’re choosing Neosurf strictly for convenience, it’s expensive—PayID costs nothing and settles faster. If you’re buying privacy (no casino transaction on your bank statement) or hard budget control (can only spend the voucher amount, no impulse re-deposits), then 3.5–15% is the cost of those features.
The fee structure matters. Buying a $100 voucher at 3.5% fee costs $3.50 for the privacy/control benefit. Buying a $10 voucher at 15% costs $1.50 for the same benefit on a much smaller deposit. The percentage hurts more on small denominations, but the absolute dollar cost is lower. Players making frequent small deposits get hit hardest—five $10 vouchers cost $7.50 in total fees (5 × $1.50), while one $50 voucher costs $2–3.
Compare to alternatives. E-wallets (Skrill, Neteller) offer similar bank-statement privacy for 2–4% in round-trip currency conversion, but they’re not deposit-only—you can withdraw to the e-wallet, then to your bank, keeping funds in play across sessions. Crypto offers even better privacy for $1–5 in network fees flat, but requires exchange accounts and comfort with blockchain transactions. Neosurf’s value proposition targets players who want cash-based deposits or who lack access to crypto exchanges and e-wallet accounts.
One hidden cost: stricter withdrawal KYC. Voucher depositors provide no bank-verified identity at deposit time (the casino just sees a redeemed Neosurf PIN), so compliance teams apply extra scrutiny at withdrawal. Expect requests for more documents—ID, proof of address, potentially a bank statement showing your nominated withdrawal account is genuinely yours. Players who upload documents proactively at registration sidestep this friction, but those who wait until requesting a cashout face delays.
Paysafecard
Paysafecard operates under Paysafe Group (same parent company as Skrill and Neteller), headquartered in Austria, regulated by the FMA (Financial Market Authority Austria). Launched in 2000, Paysafecard built a strong European footprint before expanding internationally. Australian retail distribution is less dense than Neosurf’s—you’ll find Paysafecard at some newsagents, service stations, and online resellers, but Coles and 7-Eleven don’t carry it uniformly.
Face values typically run $20, $50, $100 in the Australian market, with purchase fees of 4–10% depending on retailer and denomination. The fee is less favorable than Neosurf’s $100 tier (which hits 3.5%) but comparable at mid-range denominations. The 16-digit PIN format differs from Neosurf’s 10 digits—functionally irrelevant, just a different code to enter at the casino cashier.
Paysafecard offers a “my paysafecard” account feature that Neosurf lacks. Instead of tracking multiple physical PINs, you register an account on the Paysafecard website, load your purchased PINs into the account, and the system aggregates your balance. Casino deposits draw from the account balance rather than requiring you to enter individual PINs. The account also stores transaction history and enables direct top-ups via bank transfer in some markets (though this reintroduces the bank-statement visibility that cash vouchers avoid).
Casino acceptance sits around 30% of Australian-facing operators—substantially lower than Neosurf’s 50%+. The gap reflects Neosurf’s aggressive Australian market push and Coles partnership, while Paysafecard maintains a more international focus. For players, this means Neosurf works at more casinos; Paysafecard functions as a fallback or an option at specific operators that prefer Paysafe Group’s ecosystem (some casinos accept Paysafecard, Skrill, and Neteller as a bundle from the same payment integration).
CashtoCode
C2C Cashless Payment Solutions operates from Malta under MFSA regulation (Malta Financial Services Authority). Launched in 2015, CashtoCode uses a barcode model instead of pre-printed PINs. You generate a barcode on the CashtoCode website or via a casino’s integrated cashier, take the barcode to a participating retailer, pay cash at the counter, receive a confirmation code, enter the code at the casino. Settlement takes 2–15 minutes.
Denominations range from $10 to $200 depending on the casino’s integration. Purchase fees run around 5%, sitting between Neosurf’s low end (3.5% on $100) and Paysafecard’s mid-range (4–10%). Australian retail distribution is the weakest of the three—some service stations and newsagents participate, but the network is sparse compared to Neosurf’s Coles footprint or even Paysafecard’s reach.
Casino acceptance is under 20% of Australian-facing operators as of 2026. CashtoCode positions itself as a cash-friendly option for underbanked users and markets with limited prepaid-card infrastructure, but in Australia those niches are already well-served by Neosurf. The barcode-to-cash model has merit in theory (no need to stock physical vouchers at retailers, dynamic denomination support), but poor retail distribution and low casino integration limit its practical utility for Australian players.
Cryptocurrency: Bitcoin, Ethereum, USDT, and Emerging Coins
Cryptocurrency withdrawals are the fastest way to move money out of an online casino. Bitcoin typically clears in under 60 minutes. Tether on the Tron blockchain (USDT-TRC20) settles in under one minute. Compare that to card refunds (two to five days) or e-wallets (24 hours), and the speed advantage is clear. Deposits are equally fast—blockchain confirmation times range from seconds (Solana) to an hour (Bitcoin), with most sitting in the one-to-five-minute range.
Six cryptocurrencies dominate Australian casino acceptance: Bitcoin (70%+ of operators), Ethereum (60%+), Tether USDT (50%+), Litecoin (40%+), Bitcoin Cash (25%+), and Solana (15%+ and growing). All bypass the banking system entirely—your transaction flows from a crypto exchange or wallet to the casino’s blockchain address, no Australian bank involved. AUSTRAC requires exchanges to report fiat conversions over $10,000 under AML/CTF Act provisions, but the casino deposit itself creates no bank record.
Network fees vary wildly. Bitcoin charges $1–5 per transaction depending on blockchain congestion. Ethereum’s gas fees range $1–8. USDT-TRC20 costs under $1. Litecoin is under $0.10. Solana is under $0.01. For players making frequent small deposits, low-fee coins (USDT-TRC20, Litecoin, Solana) save significantly over Bitcoin.
Price volatility is the trade-off. Bitcoin, Ethereum, Litecoin, Bitcoin Cash, and Solana all fluctuate in value—deposit $100 of Bitcoin, win $200, withdraw, and by the time you convert back to AUD on the exchange your $200 might be worth $190 or $210 depending on how Bitcoin moved during your session. Stablecoins like USDT eliminate this: 1 USDT equals approximately 1 USD always, so your balance doesn’t shift from market volatility (though the AUD/USD exchange rate still applies when you convert back to Australian dollars).
Bitcoin (BTC)
Bitcoin launched 3 January 2009 as the first cryptocurrency, created by pseudonymous developer Satoshi Nakamoto. It remains the largest by market cap (over US$1 trillion), most liquid (easiest to buy and sell on exchanges), and most widely accepted at online casinos. Roughly 70% of Australian-facing offshore operators accept Bitcoin deposits and withdrawals as of 2026.
Deposits take 10–60 minutes depending on network congestion and the casino’s confirmation requirements. Most casinos credit your account after one to three blockchain confirmations. At Bitcoin’s 10-minute average block time, that means 10–30 minutes typical. During high-congestion periods (price spikes, high transaction volume), unconfirmed transactions can sit in the mempool for hours, though casinos usually credit after the first confirmation regardless.
Withdrawals follow the same timeline: once the casino processes your request and broadcasts the Bitcoin transaction, it confirms within 10–60 minutes. Network fees range $1–5 per transaction, paid to Bitcoin miners for processing. The fee doesn’t scale with transaction size—sending $50 or $5,000 costs the same $1–5. This makes Bitcoin economical for larger transactions but expensive for micro-deposits.
Price volatility cuts both ways. A $100 Bitcoin deposit might be worth $105 or $95 by the time you withdraw, independent of your gambling outcome. Players comfortable with this volatility—or who hold Bitcoin long-term and view casino play as spending from their existing holdings—accept the fluctuation. Risk-averse players or those depositing specifically for a session prefer stablecoins.
Australian players access Bitcoin through AUSTRAC-registered exchanges: CoinSpot, Swyftx, Independent Reserve. All three require KYC (photo ID, proof of address) and report fiat conversions over $10,000 to AUSTRAC under anti-money-laundering rules. Buying Bitcoin on the exchange, depositing to a casino, withdrawing, and selling back to AUD creates two AUSTRAC-visible events (the buy and the sell) but no record of the casino transaction itself.
Ethereum (ETH)
Ethereum launched 30 July 2015, created by Vitalik Buterin and co-founders as a blockchain platform supporting smart contracts and decentralized applications. It’s the second-largest cryptocurrency by market cap (US$300–500 billion) and accepted at roughly 60% of Australian-facing casinos—slightly lower than Bitcoin but still widespread.
Speed is Ethereum’s advantage over Bitcoin. Block times average 12–15 seconds (versus Bitcoin’s 10 minutes), and most casinos require one to three confirmations, putting total deposit time at one to five minutes. Withdrawals match that speed. Network fees (called “gas” on Ethereum) vary with blockchain congestion, ranging $1–8 per transaction. During peak periods—NFT drops, DeFi surges, major market moves—gas can spike above $20, though typical casino transaction timing avoids the worst peaks.
Ethereum’s blockchain hosts ERC-20 tokens, including USDT (Tether) and USDC (USD Coin). Casinos accepting Ethereum often accept ERC-20 tokens on the same deposit address, allowing you to deposit USDT via the Ethereum network. This flexibility matters: if you want stablecoin benefits (no price volatility) but the casino only lists “Ethereum” in its cashier, check if they accept USDT-ERC20—many do without explicitly listing it.
Price volatility historically runs higher than Bitcoin—Ethereum’s smaller market cap and different use case (platform for decentralized apps versus pure store-of-value) drive bigger percentage swings. Same trade-off as Bitcoin: your balance fluctuates with the market, beneficial if ETH rises during your session, costly if it falls.
Litecoin (LTC)
Litecoin launched 13 October 2011, created by Charlie Lee as a “lighter” version of Bitcoin—faster block times (2.5 minutes versus Bitcoin’s 10), lower fees, same security model. Market cap sits around US$5–10 billion, substantially smaller than Bitcoin or Ethereum. Casino acceptance reaches 40%+ of Australian-facing operators, lower than BTC/ETH but sufficient for most players.
The value proposition is cost. Litecoin network fees are under $0.10 per transaction, dramatically cheaper than Bitcoin’s $1–5 or Ethereum’s $1–8. For players making multiple small deposits, Litecoin saves real money. A player depositing $50 five times pays $25 in total Bitcoin fees ($5 × 5) versus $0.50 in Litecoin fees ($0.10 × 5)—a $24.50 difference that’s pure savings.
Speed sits between Bitcoin and Ethereum. Litecoin’s 2.5-minute block time with one to three confirmations puts deposits at 2–10 minutes typically. Withdrawals match. Faster than Bitcoin, slightly slower than Ethereum, but the difference is marginal in practical terms—all three settle within minutes to tens of minutes.
Price volatility is moderate. Litecoin tracks Bitcoin directionally (when BTC rises, LTC tends to rise; when BTC falls, LTC falls) but with higher percentage swings due to lower liquidity. The volatility risk is equivalent to Bitcoin; the fee advantage is the differentiator.
Tether (USDT)
Tether (USDT) is a stablecoin pegged 1:1 to the US dollar, issued by Tether Limited (a British Virgin Islands company). Launched in 2014, USDT is the largest stablecoin by market cap (over US$120 billion) and the third-largest cryptocurrency overall behind Bitcoin and Ethereum. It operates on multiple blockchains—most relevantly for casino players, Ethereum (ERC-20) and Tron (TRC-20).
The stablecoin mechanism eliminates price volatility. 1 USDT equals 1 USD always (barring catastrophic de-pegging events, which haven’t occurred durably despite periodic market scares). For Australian players, this means your balance stays constant in USD terms—deposit $100 AUD worth of USDT, that converts to roughly 65 USDT at typical AUD/USD exchange rates, and those 65 USDT remain 65 USDT regardless of crypto market swings. The AUD/USD exchange rate still applies when converting back to Australian dollars, but you’re not exposed to Bitcoin’s 5–10% daily price swings.
USDT-TRC20 (Tron blockchain) became the preferred crypto rail for Australian casino players during 2024–2026, overtaking Bitcoin for speed-conscious users. Settlement time is under one minute—Tron’s blockchain confirms in seconds, and most casinos credit after one confirmation. Network fees are under $1 per transaction, cheaper than Bitcoin and Ethereum. The combination of instant settlement, near-zero fees, and zero price volatility makes USDT-TRC20 functionally superior to Bitcoin for casino transactions, with the sole limitation being slightly lower casino acceptance (50% versus Bitcoin’s 70%).
USDT-ERC20 (Ethereum blockchain) is the same stablecoin on a different network. Fees are higher ($1–6 depending on Ethereum gas prices), settlement is slower (one to five minutes), but casino acceptance is broader because many operators support Ethereum and accept ERC-20 tokens by default. The critical error: network mismatch. Sending USDT-ERC20 to a TRC-20 address results in permanent loss—the funds vanish into an incompatible blockchain address with no recovery mechanism. Always verify which USDT network the casino supports before sending. When in doubt, ask support or check the deposit address format (TRC-20 addresses start with “T”, ERC-20 start with “0x”).
Australian exchanges (CoinSpot, Swyftx, Independent Reserve) all support USDT. Buying USDT on the exchange, selecting TRC-20 as the withdrawal network, sending to the casino’s TRC-20 address, playing, withdrawing back to your exchange TRC-20 address, selling to AUD—total fees are under $2 plus exchange spread, and total time is under 10 minutes for the round trip once the casino processes your withdrawal.
Bitcoin Cash (BCH)
Bitcoin Cash forked from Bitcoin on 1 August 2017 following a contentious community debate over block size. The fork increased block capacity to enable more transactions per second and lower fees. Market cap sits around US$5–10 billion, and casino acceptance reaches 25% of Australian-facing operators—the lowest of the major coins discussed here.
The original value proposition was “cheaper Bitcoin”—same security model, lower fees. But that advantage eroded as USDT-TRC20 and Litecoin offered even lower fees (under $1 and $0.10 respectively versus Bitcoin Cash’s $0.10–1), and as Bitcoin’s Layer-2 solutions (Lightning Network) addressed the fee problem Bitcoin Cash was created to solve. By 2026, Bitcoin Cash occupies an awkward middle ground: more expensive than Litecoin and USDT-TRC20, less accepted than Bitcoin, no clear differentiation.
Speed and fees sit at 10–30 minutes settlement and $0.10–1 network fees. Faster and cheaper than Bitcoin, but not faster or cheaper enough to displace the alternatives. Price volatility is high—BCH’s smaller market cap and lower liquidity drive larger percentage swings than Bitcoin.
For Australian players, Bitcoin Cash functions as a fallback option. If a casino accepts BCH but not USDT-TRC20 or Litecoin, it’s viable. But given the choice, most players opt for faster and cheaper alternatives.
Solana (SOL)
Solana launched in March 2020, created by Solana Labs as a high-speed blockchain platform. It processes transactions in under one second with network fees under $0.01—the fastest and cheapest of all major casino-compatible cryptocurrencies. Market cap ranges US$40–80 billion (top 10 crypto), and casino acceptance is growing rapidly: roughly 15% of Australian-facing operators as of 2026, up from around 5% in 2024.
The speed advantage is measurable. Solana deposits confirm in under one minute, often within 10–20 seconds. Withdrawals match. Network fees are negligible—$0.001 to $0.01, effectively free compared to Bitcoin’s $1–5 or Ethereum’s $1–8. For players prioritizing absolute speed and minimum cost, Solana delivers better metrics than any alternative including USDT-TRC20.
The trade-off is network history. Solana suffered multiple outages during 2021–2022—the longest lasted 17 hours in September 2021—due to congestion and software bugs. Network stability improved dramatically in 2023 and has remained solid through 2026, but the reputation damage lingers. Casinos hesitated to integrate Solana during the outage period, which explains the lower acceptance rate compared to older coins.
Price volatility is high. Solana is newer, smaller market cap, and more speculative than Bitcoin or Ethereum. Expect larger percentage swings. Stablecoin users should stick with USDT; Solana appeals to crypto-native players who already hold SOL and want the fastest possible cashout.
Casino integration is accelerating. Newer operators launch with Solana support as a competitive differentiator, advertising “under 1 minute withdrawals” powered by Solana’s speed. Expect acceptance to climb toward 30–40% by 2027 if network stability holds.
Which cryptocurrency is best for Australian casino players?
USDT-TRC20 for most players: stablecoin eliminates price volatility, Tron blockchain settles in under one minute, network fees are under $1, and 50% casino acceptance is sufficient for mainstream operators. You avoid Bitcoin’s price swings and high fees, and you avoid Ethereum’s gas-fee variability.
Bitcoin if casino acceptance is your priority: 70% of operators accept Bitcoin, the highest of any crypto. If you’re trying multiple casinos or using niche operators, Bitcoin ensures compatibility. The fee penalty ($1–5 versus USDT-TRC20’s under $1) and slower speed (10–60 minutes versus under 1 minute) are acceptable costs for maximum optionality.
Litecoin for micro-stakes players: if you’re depositing $20–50 multiple times per session, Litecoin’s $0.10 fee saves meaningful money compared to Bitcoin’s $5. Acceptance is lower (40%) but still broad enough for most Australian-facing casinos.
Solana if you’re chasing absolute speed and already hold SOL: sub-second settlement and $0.01 fees beat everything else, but 15% acceptance limits your casino choices. Ideal for players using Solana-friendly operators and comfortable with the network’s shorter track record.
Ethereum if you’re already holding ETH or need ERC-20 token compatibility: faster than Bitcoin (1–5 minutes), but gas fees ($1–8) are higher than USDT-TRC20. Choose Ethereum if the casino accepts ETH but not TRC-20, or if you’re holding ETH long-term and want to spend from existing holdings.
Bitcoin Cash is the fallback: only choose BCH if the casino doesn’t accept any of the above. No compelling reason to select it otherwise.
Bank Transfers: BPAY, POLi, Trustly, and Traditional BSB Transfers
Bank transfers predate PayID and still function as high-limit, low-tech deposit options. Four variants exist in the Australian casino context: BPAY (bill-payment system, 1–2 days), POLi (shut down September 2023, do not use), Trustly (international instant bank transfer, limited Australian acceptance), and traditional bank transfer via BSB and account number (1–3 days, highest limits).
BPAY
BPAY launched in 1997 as Australia’s electronic bill-payment system, managed by what’s now Australian Payments Plus (the same entity running PayID). It allows paying bills via a biller code (unique merchant identifier) and reference number (unique customer identifier) entered in your banking app or internet banking.
Casinos with BPAY integration register as BPAY billers and display their biller code in the deposit cashier alongside a unique reference number for your account. You log into your bank, select BPAY payment, enter the biller code and reference, specify the amount, confirm. Settlement takes one to two business days—not instant like PayID, but faster than international wire transfers.
Daily limits are high. NAB and Westpac allow $100,000 BPAY transfers per day, substantially higher than their PayID limits ($25,000 and $20,000 default respectively). CBA and ANZ cap BPAY around $25,000, matching their PayID limits. For players depositing large amounts—high rollers, tournament buy-ins, VIP-table bankrolls—BPAY’s high limits and bank-direct routing offer advantages over intermediate methods like e-wallets.
Casino acceptance is declining. Roughly 20% of Australian-facing operators accept BPAY as of 2026, down from around 40% in 2020. The drop reflects PayID’s instant settlement advantage—casinos prefer rails that credit deposits immediately, and players prefer not waiting one to two days. BPAY persists as a backup option for players who’ve exhausted PayID limits or whose banks block PayID gambling transactions but haven’t extended the block to BPAY.
Fees are typically zero from the user’s perspective (banks don’t charge BPAY transaction fees to customers). Deposits-only at most casinos; few operators support BPAY withdrawals.
POLi (Discontinued September 2023)
POLi Payments operated an instant bank-transfer service from 2006 to September 2023 using a screen-scraping model: users entered their internet banking credentials on POLi’s site, POLi logged into the bank on their behalf, POLi executed the payment. Settlement was under 60 seconds, zero fees, and POLi dominated the Australian instant-deposit niche before PayID existed.
Australian Payments Plus acquired POLi in July 2020 and shut it down permanently on 30 September 2023. The official reason: screen-scraping conflicted with modern banking security standards, violated bank terms of service (users aren’t supposed to share login credentials), and became redundant once the NPP/PayID infrastructure offered instant bank transfers without credential-sharing risks.
Any casino still listing POLi in 2026 runs outdated information or fraudulent processes. POLi does not function. Polipayments.com redirects to Australian Payments Plus with a discontinuation notice. Do not attempt to use POLi. If a casino’s cashier shows POLi as an active option, contact support before attempting a deposit—it’s a red flag suggesting the operator hasn’t updated its payment integrations in years.
PayID replaced POLi functionally. Same instant settlement, same zero fees, same bank-direct routing, but without the security nightmare of entering your bank password on a third-party site. Players who used POLi before its 2023 shutdown should switch to PayID; the experience is nearly identical minus the credential risk.
Trustly
Trustly Group operates from Sweden as an FSA-regulated payment institution, listed on Nasdaq Stockholm since 2021. The service offers instant bank-to-bank transfers similar to what POLi attempted, but using bank API integrations instead of screen scraping. Users are redirected to their bank’s official login page (Trustly doesn’t handle credentials), authorize the transaction within the bank’s interface, and the payment settles instantly.
Australian casino acceptance is limited—under 10% of operators as of 2026. The low adoption reflects Trustly’s EU focus and PayID’s dominance in the Australian market. Casinos that do accept Trustly are typically EU-headquartered operators that also serve Australian players and wanted a unified instant-bank-transfer solution across markets.
Trustly works with major Australian banks (CBA, NAB, Westpac, ANZ) where integrated. Fees are typically zero for users (the merchant pays). Deposits and withdrawals are both supported (bi-directional), giving Trustly an advantage over vouchers. Settlement is instant—under 60 seconds for both directions.
For Australian players, Trustly functions as a PayID alternative at the small number of casinos that accept it. No compelling reason to choose Trustly over PayID if both are available, but if a casino lists Trustly and not PayID (rare but possible at EU-focused operators), Trustly delivers equivalent instant-settlement performance.
Traditional Bank Transfer via BSB
Traditional bank transfer—entering a BSB, account number, and reference in your internet banking—remains available at most casinos as a fallback option. Settlement takes one to three business days depending on whether the casino’s receiving bank is Australian or offshore. Limits are the highest of any method: Westpac allows $100,000 daily transfers, NAB and ANZ similar. No intermediary, no fees from the user’s bank (though the casino’s receiving bank may deduct international wire fees from large transfers).
The use case is niche: players depositing amounts above PayID limits ($25,000+), players whose banks block PayID for gambling, players uncomfortable with crypto or e-wallets who accept the delay in exchange for traditional banking familiarity. Casinos display their bank details (often a bank account in Curaçao, Malta, or Cyprus), you initiate the transfer, the casino credits your account once the funds arrive and are reconciled (one to three days).
Withdrawals via traditional bank transfer follow the same timeline. The casino initiates an international wire to your Australian BSB and account number, the transfer takes one to three business days, funds appear in your account. Some casinos charge withdrawal fees for bank transfers ($10–50 flat fee) where PayID and crypto are free.
Mobile Wallets: Apple Pay and Google Pay
Apple Pay and Google Pay both offer tokenized card payments for online transactions. You link your credit or debit card to the wallet app, the wallet generates a tokenized card number, the casino processes the payment against the token. The casino never sees your actual card number—slightly more secure than entering your card directly.
The limitation: Apple Pay and Google Pay don’t bypass bank-side gambling blocks. The underlying card’s issuing bank still sees MCC 7995 and applies its policy. If Commonwealth Bank blocks gambling on your debit card, Apple Pay using that CBA debit card also gets blocked. The tokenization provides security against card-number theft but doesn’t circumvent regulatory or policy restrictions.
Apple Pay
Apple Pay launched in Australia in September 2015. It works on iPhones, iPads, and Apple Watches. Casino acceptance sits under 15% of Australian-facing operators as of 2026—low adoption driven by Apple’s restrictive gambling-merchant policies and the fact that Apple Pay offers no functional advantage over direct card entry or PayID for Australian players.
Deposits are instant when they work. Fees match the underlying card (many casinos charge 1–3% for card deposits). Withdrawals are rare—most casinos treat Apple Pay deposits as card transactions and refund via the original card, not via Apple Pay as a distinct rail. Minimum deposits typically $10–20.
The value proposition is convenience for iOS users: Face ID or Touch ID authentication, no need to enter card numbers. But that convenience doesn’t overcome the bank-block problem or the low casino acceptance. PayID is faster, free, and accepted more broadly.
Google Pay
Google Pay launched in Australia in 2016 as Android Pay, rebranded to Google Pay in 2018. It’s the Android equivalent of Apple Pay—tokenized card payments, NFC for in-store purchases, online checkout integration. Casino acceptance is marginally higher than Apple Pay (still under 15%) due to Android’s larger Australian market share, but remains niche.
Deposits instant, fees match underlying card, withdrawals rare. Same bank-block limitations as Apple Pay. Same lack of differentiation versus PayID or direct card entry.
For Australian players, Google Pay functions as a minor convenience if you’re already using it for other online purchases and happen to find a casino that accepts it. Not a payment method to seek out specifically.
Deposits vs Withdrawals: What You Need to Know
Not every deposit method supports withdrawals. Prepaid vouchers (Neosurf, Paysafecard, CashtoCode) are deposit-only—you can load money in, but you cannot cash out to a voucher. Mobile wallets (Apple Pay, Google Pay) rarely support withdrawals despite accepting deposits. BPAY is primarily deposit-only, though a handful of casinos process BPAY refunds.
This asymmetry forces players using deposit-only methods to nominate an alternative withdrawal method during account setup or before requesting their first cashout. A player who deposits exclusively with Neosurf must provide bank account details (for traditional transfer or PayID), a crypto wallet address, or an e-wallet account when withdrawing. The casino cannot send money back to a voucher PIN.
Deposit-Only Methods and Withdrawal Alternatives
Vouchers, cards, and mobile wallets create a split-payment workflow. Deposit via Neosurf for privacy and budget control, withdraw via PayID for speed. Deposit via Apple Pay for convenience, withdraw via bank transfer or crypto. The casino’s payment processor handles this mismatch, but it introduces friction—more methods to verify during KYC, more accounts to maintain, more steps in the cashout process.
The cleanest workflows use bi-directional methods: PayID deposits and PayID withdrawals (same rail both directions), crypto deposits and crypto withdrawals (same wallet), e-wallet deposits and e-wallet withdrawals (same Skrill account). One method, one set of credentials, one KYC verification. Deposit-only methods sacrifice this simplicity for their specific benefits (voucher privacy, card familiarity).
Some casinos restrict withdrawal methods based on deposit method. A common policy: “withdrawals must use the same method as deposits where possible, alternative methods only for deposit-only rails.” This prevents certain money-laundering patterns (deposit via stolen card, withdraw via crypto) but complicates legitimate mixed-method usage. Check the casino’s terms before depositing if you plan to withdraw via a different method—some operators require depositing via the intended withdrawal method at least once to “verify” it.
First Withdrawal and KYC Requirements
Know Your Customer verification triggers before your first withdrawal at every licensed casino. The Interactive Gambling Act doesn’t mandate this—Australia doesn’t license online casinos domestically—but the casino’s offshore jurisdiction (Curaçao, Malta, Gibraltar) imposes AML/CTF obligations that require verifying player identity before processing payouts.
Standard KYC documents: government-issued photo ID (passport or driver’s license), proof of address (utility bill, bank statement, government letter dated within the last three months), proof of payment method (bank statement showing the deposit, screenshot of e-wallet account, photo of card used for deposits with middle digits obscured). Upload quality matters—blurry photos, cropped edges, unreadable text all trigger rejection and re-upload requests.
Voucher-only depositors face stricter verification. The casino received a redeemed Neosurf PIN with no bank-verified identity attached, so compliance teams apply extra scrutiny. Expect requests for additional documents (secondary ID, additional proof of address, video verification in some cases) and longer processing times. This isn’t arbitrary harassment—it’s regulatory requirement. Casinos operating under Malta or Curaçao licenses must demonstrate they verified the player’s identity before paying out, and voucher deposits provide less initial verification than bank transfers or cards.
PayID depositors benefit from built-in verification. The NPP infrastructure transmits the account holder’s name with every transaction (Confirmation of Payee data), so the casino knows your bank account name matches your casino account name from the first deposit. KYC is still required, but the bank-verified identity at deposit time reduces the compliance team’s burden and speeds approval.
Upload documents before depositing, not when requesting your first withdrawal. Most casinos allow uploading ID proactively during or immediately after registration. Documents sit in the verification queue, compliance reviews them within 12–72 hours, your account gets marked as verified. When you request your first withdrawal, you skip the document-upload step and the verification delay—straight to payout processing. The alternative: deposit, play, win, request withdrawal, then upload documents, wait 24–72 hours for review, finally receive payout. Uploading early cuts two days off your first cashout.
Do I need to verify my identity (KYC) before withdrawing from an online casino?
Yes, at every licensed casino. The verification happens before your first withdrawal, not before depositing. You can deposit and play without KYC, but the payout triggers document requests.
Some casinos implement tiered KYC: micro-withdrawals (under $500–1,000) may process with minimal verification (ID only), while larger withdrawals require full documentation (ID, proof of address, payment method verification). The threshold varies by operator and license jurisdiction. VIP players and high rollers undergo enhanced due diligence regardless of withdrawal size.
Unlicensed casinos—operations with no Curaçao, Malta, or other recognized license—sometimes advertise “no KYC” or “anonymous play.” These operators either don’t process withdrawals reliably or are exit-scam risks. Licensed casinos cannot offer genuine no-KYC withdrawals and remain compliant with their license conditions. The trade-off for regulatory legitimacy is mandatory identity verification.
Can I deposit and withdraw using different payment methods?
Yes, but with caveats. Most casinos allow it, some impose restrictions, and doing so often triggers additional verification steps.
Common restrictions: “Withdrawals must use the same method as deposits where possible.” This means if you deposited via PayID, the casino prefers (or requires) you withdraw via PayID. Alternative methods are permitted only when the deposit method doesn’t support withdrawals (vouchers, some cards) or when you provide a compelling reason (account closed, method no longer available).
The compliance logic: mixed-method transactions can indicate money laundering (deposit via stolen card, withdraw via crypto to obscure the trail). Casinos apply extra scrutiny when deposit and withdrawal methods don’t match. Expect document requests proving ownership of both methods—bank statement showing the deposit, screenshot of the crypto wallet or e-wallet account receiving the withdrawal, written explanation of why you’re changing methods.
Best practice: deposit via your intended withdrawal method at least once, even if you primarily use a different method. Deposit $10 via PayID to verify it, use Neosurf for your main session, withdraw via the verified PayID. This satisfies the “same method” policy on paper while letting you use your preferred deposit rail.
Mixed-Method Payouts
Some casinos split large withdrawals across multiple methods automatically. A $10,000 cashout might go $5,000 to your PayID, $5,000 to crypto, based on daily processing limits for each rail. Other operators let you nominate multiple withdrawal methods and split the amount manually.
Mixed-method payouts can speed up large cashouts by utilizing multiple rails’ daily limits simultaneously. PayID might cap at $5,000 per transaction, but PayID + crypto lets you withdraw $10,000 in one request. The trade-off: more verification (both methods must be KYC-approved), more accounts to monitor (check your bank and your crypto exchange for incoming funds), more reconciliation if something goes wrong.
Withdrawal Speed Comparison: Which Methods Are Fastest?
Withdrawal speed has two components: casino processing time (how long the casino takes to approve and initiate your payout) and payment rail settlement time (how long the payment method takes to deliver funds to your account). Marketing claims focus on the second while the first determines your actual experience.
A casino advertising “instant PayID withdrawals” might process your request in 10 minutes or 10 hours depending on its internal procedures. PayID’s rail settlement is always instant (under 60 seconds on the NPP), but that matters only after the casino broadcasts the payment. Operator processing time varies 5× to 20× between fast and slow casinos on identical payment rails.
Tested Withdrawal Times by Method
Hell Spin PayID: 25 minutes total from withdrawal request to funds in bank account. Goldenbet PayID: 28 minutes. Lucky7 PayID: 35 minutes. These are automated-approval operators—verified accounts under certain thresholds (typically $5,000–10,000) get instant approval, the payout broadcasts immediately, NPP settles in under a minute.
Wintino PayID: 2–3 hours total. Joe Fortune PayID: 3–5 hours. These are batch-processing operators—withdrawals queue for manual review or fixed payout windows (every 2 hours, every 6 hours), then broadcast, then NPP settles instantly. The 2–5 hour span is operator delay, not PayID delay.
Lucky7 USDT-TRC20: 14 minutes total. Typical Bitcoin withdrawal: 10–60 minutes total depending on network congestion. Fast operators (automated approval) process crypto within minutes; slow operators queue for hours before broadcasting the blockchain transaction.
E-wallet withdrawals (Skrill, Neteller, PayPal, ecoPayz, MiFinity): 24 hours typical for most casinos. The operator approves the withdrawal (hours to one day), broadcasts to the e-wallet (instant), you transfer from e-wallet to bank (one to three business days). Total end-to-end: one to four days.
Card refunds: two to five business days from approval to funds posting to your card. The casino initiates a reversal transaction, the card network processes it through its settlement cycle, your bank posts the credit. Fastest card refunds: two business days. Typical: three to four days. Slowest: five days.
Traditional bank transfer: one to three business days depending on whether the casino’s bank is Australian (one day) or offshore (two to three days for international wire). High-limit option but slowest common method.
| Method | Operator Processing (typical) | Rail Settlement Time | Total End-to-End | Tested Examples (2026) |
|---|---|---|---|---|
| PayID (fast operators) | 10–30 min | <1 min | 10–35 min | Hell Spin 25 min, Goldenbet 28 min, Lucky7 35 min |
| PayID (batch operators) | 1–4 hours | <1 min | 1–4 hours | Wintino 2–3 hours, Joe Fortune 3–5 hours |
| USDT-TRC20 | 10–60 min | <1 min | 10–60 min | Lucky7 14 min |
| Bitcoin | 30 min–4 hours | 10–60 min | 40 min–5 hours | Typical 1–2 hours total |
| Ethereum | 30 min–4 hours | 1–5 min | 30 min–4 hours | Similar to Bitcoin |
| Litecoin | 30 min–4 hours | 2–10 min | 30 min–4 hours | Similar to Bitcoin |
| Solana | 10–60 min | <1 min | 10–60 min | Similar to USDT-TRC20 where accepted |
| Skrill | 4–24 hours | Instant | 4–24 hours + 1–3 days to bank | Typical 24 hours to e-wallet |
| Neteller | 4–24 hours | Instant | 4–24 hours + 1–3 days to bank | Typical 24 hours to e-wallet |
| PayPal | 4–72 hours | Instant | 4–72 hours + 1–3 days to bank | Slower than Skrill/Neteller |
| ecoPayz | 4–24 hours | Instant | 4–24 hours + 1–3 days to bank | Typical 24 hours to e-wallet |
| MiFinity | 4–24 hours | Instant | 4–24 hours + 1–3 days to bank | Typical 24 hours to e-wallet |
| Visa/Mastercard Debit | 12–48 hours | 2–5 business days | 2–6 business days | Bank-dependent, CBA faster than regionals |
| Bank Transfer | 12–48 hours | 1–3 business days | 2–5 business days | Offshore wires slower than domestic |
| BPAY | Rare | 1–2 business days | 2–3 business days | Few casinos support BPAY withdrawals |
The table makes clear: operator processing time dominates the experience. Hell Spin’s 25-minute PayID withdrawal versus Wintino’s 2–3-hour PayID withdrawal is a 5× difference on identical infrastructure. USDT-TRC20’s sub-minute blockchain settlement matters only if the casino approves and broadcasts quickly.
Why Operator Processing Time Matters More Than Rail Speed
PayID settles in under 60 seconds on the New Payments Platform. But if the casino holds your withdrawal for manual compliance review for six hours, you wait six hours. The NPP’s speed is irrelevant until the casino broadcasts the payment.
Bitcoin confirms in 10–60 minutes on the blockchain. But if the casino queues crypto withdrawals for batch processing every 12 hours, you wait 12 hours plus the blockchain time. The batch cycle determines your experience, not Bitcoin’s block time.
Fast operators run automated approval systems: verified accounts under certain thresholds trigger instant approval and immediate broadcast. You request withdrawal, the system checks your verification status and withdrawal amount, approves automatically if both clear the threshold, broadcasts the payment to PayID or crypto within minutes. Total time: rail settlement + a few minutes overhead.
Slow operators run manual approval: every withdrawal lands in a queue, a compliance officer or finance team member reviews it (checking for bonus abuse, duplicate accounts, suspicious patterns), manually approves, the system broadcasts. Queue depth and staff availability determine your wait—submit your withdrawal during peak hours (evening AEST) and you might wait four hours for review, submit overnight and you wait until the next business day.
VIP players and high rollers often bypass standard queues. Casinos offer dedicated account managers and priority processing for players depositing above certain thresholds ($10,000+, $50,000+, $100,000+ depending on the operator’s tier structure). The same withdrawal that takes a standard player three hours processes in 10 minutes for a VIP because it routes to a priority queue.
Which payment methods are fastest for withdrawals at Australian online casinos?
USDT-TRC20 and PayID at fast operators: both deliver sub-hour total times (10–35 minutes for PayID at Hell Spin/Goldenbet/Lucky7, 10–60 minutes for USDT-TRC20). The casino processing time matters more than the rail—choose casinos with automated approval for verified accounts rather than optimizing the payment method alone.
Bitcoin, Ethereum, Litecoin, Solana at fast operators: all settle within one to two hours total when the casino processes quickly. Bitcoin’s 10–60-minute blockchain time is the longest of the group, but still competitive with PayID at slow operators (which take 2–3 hours despite PayID’s instant rail).
E-wallets (Skrill, Neteller, ecoPayz, MiFinity): expect 24 hours to the e-wallet, then another one to three business days to transfer to your Australian bank. Slower than crypto and PayID but faster than cards.
Cards and bank transfers: slowest options at two to five business days. Only choose these if you lack access to faster methods or if withdrawal limits and fees favor them for large cashouts.
The actionable insight: test the casino’s processing speed on a small withdrawal before depositing large amounts. Withdraw $50–100 via your preferred method, measure the total time to your account. Fast processing on the test withdrawal signals the operator’s systems are automated and efficient. Slow processing (over four hours for PayID/crypto, over 48 hours for e-wallets) suggests manual queues and batch cycles—factor that delay into your session planning.
Choosing the Right Payment Method: A Decision Framework
No single payment method is optimal for every player. The right choice depends on your priorities: speed, privacy, budget control, ease of use, or large-amount capacity. Five decision frameworks cover the common priority sets.
Speed Priority
If withdrawal speed is your primary concern—you want money in your bank account within an hour of requesting cashout—narrow to PayID and USDT-TRC20 at casinos with fast processing. Test a small withdrawal first. Hell Spin, Goldenbet, and Lucky7 delivered sub-35-minute PayID withdrawals in 2026 testing; expect similar performance from other casinos advertising “instant withdrawals” with verified player reviews confirming it.
USDT-TRC20 offers comparable speed (10–60 minutes total at fast operators) with the added benefit of bypassing the banking system. If you’re comfortable with crypto exchanges (CoinSpot, Swyftx, Independent Reserve), USDT-TRC20 is marginally faster than PayID at the fastest casinos and avoids bank-statement visibility.
Avoid: e-wallets (24+ hours), cards (two to five days), bank transfers (two to five days), BPAY (one to three days). Even the fastest operators cannot speed up card network settlement cycles or international wire processing.
Privacy Priority
If minimizing bank-statement visibility is your priority—shared accounts, household budgeting, tax simplicity—choose vouchers (Neosurf, Paysafecard) for deposits and crypto (USDT-TRC20, Bitcoin, Solana) for withdrawals.
Neosurf purchased with cash leaves no bank record of the casino transaction. The retailer purchase shows as a prepaid product (MCC 5947), not gambling. Redeeming the voucher at a casino happens outside your bank’s view. Withdraw via USDT-TRC20 to an Australian exchange (CoinSpot, Swyftx), convert to AUD, transfer to your bank. Your bank statement shows “Neosurf” (gift card purchase) and “CoinSpot” (exchange transfer), never the casino’s name or gambling-related merchant codes.
E-wallets (Skrill, Neteller, MiFinity) offer partial privacy: your bank sees transfers to the e-wallet provider, not the casino. The casino transaction happens inside the e-wallet. Less private than vouchers + crypto (because “Skrill Limited” on your bank statement still signals online payments and can be questioned), but more private than PayID or card deposits that show casino descriptors or offshore payment processors.
Cost of privacy: vouchers charge 3.5–15% purchase fees, e-wallets charge 2–4% in round-trip currency conversion, crypto charges $1–5 in network fees. PayID costs zero. Privacy has a price.
Budget Control Priority
If hard session limits and preventing impulsive re-deposits is your priority—problem gambling controls, strict bankroll management, shared-account oversight—choose vouchers (Neosurf, Paysafecard) and resist the temptation to maintain a balance in instant-deposit methods.
Buy a $100 Neosurf voucher, deposit the full $100, play. Win or lose, you cannot deposit more without physically returning to Coles and purchasing another voucher. That friction—the 10-minute drive, the counter interaction, the moment to reconsider—interrupts impulsive chasing losses. PayID, crypto, cards, and e-wallets all allow instant re-deposits from your phone during a session. Vouchers force a break.
The fee (3.5% on a $100 voucher) is a budget-control insurance premium. Paying $3.50 to lock in a $100 session limit is cheaper than the alternative (unrestricted access leading to a $500 loss chasing the $100).
Supplement vouchers with withdrawal-method preparation. Set up PayID or crypto as your cashout rail before depositing, upload KYC documents proactively, verify everything works. Fast withdrawals enable taking winnings off the table immediately, turning a $200 profit into money in your bank account within an hour. The combination—voucher budget caps on the way in, fast PayID/crypto on the way out—gives you both control and liquidity where it matters.
Ease of Use Priority
If simplicity is your priority—you want one method, minimal setup, no crypto exchanges or e-wallet registrations—choose PayID. It’s the native Australian banking rail, already built into your existing bank app, zero setup beyond registering your mobile number as a PayID (which most banks do automatically or with one tap).
Deposit flow: casino cashier → copy reference code → open bank app → PayID transfer → paste reference → authorize → done. Three minutes total. Withdrawal flow: casino cashier → request PayID withdrawal → funds arrive in your bank account → done. Ten minutes to four hours depending on the operator.
One method handles deposits and withdrawals. One set of account details (your mobile number as PayID). One KYC verification (your bank account name matches your casino account name from the first deposit). No currency conversion, no network-selection errors, no e-wallet balances to manage, no voucher PINs to track.
The simplicity trade-off: PayID shows casino transactions on your bank statement, and your bank may profile gambling patterns and reduce limits. If bank-statement visibility isn’t a concern and you’re banking with NAB, Westpac, or ANZ (which allow debit gambling transactions), PayID is the path of least resistance.
Large Amounts Priority
If you’re depositing or withdrawing amounts above $25,000—high-roller sessions, tournament entries, VIP play—narrow to methods with high limits and low percentage fees: traditional bank transfer (BSB and account number), BPAY (at banks offering $100,000 daily limits), or crypto (Bitcoin, Ethereum, USDT with no upper limit beyond exchange daily caps).
PayID caps at $25,000 default (NAB, ANZ) with uplift to $40,000–50,000. That’s insufficient for five-figure deposits. Traditional bank transfer via BSB imposes no technical limit—you can send $100,000 in one transaction at Westpac, NAB, or ANZ. Settlement takes one to three days, but the rail handles the volume without fees from your bank.
Crypto scales without percentage fees. Bitcoin charges $1–5 per transaction whether you’re sending $500 or $50,000. USDT-TRC20 charges under $1. A $50,000 withdrawal via Bitcoin costs $5 in network fees (0.01%), versus $500–1,500 if you used an e-wallet charging 1–3% currency conversion. For amounts above $10,000, crypto’s flat-fee structure saves significantly over percentage-based methods.
AUSTRAC reporting applies: crypto exchanges must report fiat conversions over $10,000 to AUSTRAC under AML/CTF provisions. This isn’t a block—you can deposit and withdraw $50,000 or $500,000—but the exchange files reports. Traditional bank transfers over $10,000 to offshore recipients also trigger reporting. High-value transactions are legal and processed normally; they’re just not private from a regulatory standpoint.
VIP programs at casinos often negotiate custom limits and fee waivers for high rollers. If you’re regularly moving five- or six-figure sums, contact the casino’s VIP team directly—they’ll arrange higher PayID limits, waived withdrawal fees, priority processing, and sometimes private payment rails (direct wire, cryptocurrency over-the-counter desks) not available to standard players.
Legal Context: Australian Regulation and Offshore Operators
The Interactive Gambling Act 2001 (IGA) is the federal law governing online gambling in Australia. It prohibits operators from offering online casino games—pokies, table games, live dealer—to persons physically in Australia. The prohibition targets operators, not players. Australian residents are not committing an offense by using offshore casinos; the operators are committing an offense by serving them.
No online casino holds an Australian license because the IGA prohibits issuing such licenses. Every real-money online casino serving Australian players operates from an offshore jurisdiction—commonly Curaçao, Malta, Gibraltar, Kahnawake, or other recognized gambling regulators. These operators market to Australians and process Australian-dollar transactions despite not holding Australian licenses, creating a gray-market situation: legal for players to use, illegal for operators to provide, effectively unenforced.
The Interactive Gambling Act 2001
The IGA targets three categories: online casino games (prohibited), online poker (prohibited), and online sports and race betting (permitted under state licenses). The distinction is arbitrary from a harm-minimization perspective but strict in application. An operator offering pokies or blackjack to Australians violates the IGA. The same operator offering sports betting with an NT or state license operates legally.
Enforcement mechanisms: ACMA (Australian Communications and Media Authority) blocks access to non-compliant gambling websites under Section 313 of the Telecommunications Act. ISPs receive blocking orders, implement DNS and IP blocks, redirect users to an ACMA notice page. As of 2026, ACMA has blocked over 1,000 domains. The blocks are trivial to bypass (VPN, DNS change, direct IP access), and offshore operators simply register new domains faster than ACMA blocks them. The system is theater more than barrier.
Prosecution of players: never happened. The IGA’s penalties apply to operators, advertisers, and payment processors facilitating illegal services. No Australian player has been fined or charged for placing a bet at an offshore casino. The regulatory focus is supply-side (making it harder for operators to market and process payments), not demand-side.
Credit Card Ban (2024)
The Interactive Gambling Amendment (Credit and Other Measures) Act 2023 banned credit cards and credit-related products for online wagering effective 11 June 2024. The ban arose from harm-minimization concerns—problem gamblers using credit to chase losses, accumulating debt, worsening addiction outcomes.
The ban is absolute: all credit cards issued in Australia, all online wagering (casinos, sports, poker, racing), all transactions regardless of operator location or license status. Debit cards, bank transfers, e-wallets, and crypto remain legal. The ban targets credit specifically, not gambling payments generally.
Banks enforced the ban by blocking MCC 7995 (gambling) on credit cards at the network level. Some banks (Commonwealth, ING) extended the block voluntarily to debit cards ahead of any requirement. The federal ban applies only to credit; debit blocks are individual bank policy.
Why Offshore Operators
Australian players use offshore casinos because domestic licensed options don’t exist. The IGA prohibits local licensing of online casino services. Sports and race betting are licensed (via state regulators and the NT), but pokies, blackjack, roulette, baccarat, and other casino games are not. A player wanting to play pokies online has no legal domestic option and must use an offshore operator.
Offshore operators accept this risk—they’re technically violating Australian law by serving Australian customers, but they operate from jurisdictions where serving Australians is legal under local law. Curaçao doesn’t prohibit operators from accepting Australian players. Malta doesn’t. Gibraltar doesn’t. The operators hold valid licenses in their home jurisdictions, comply with those regulators’ standards, and market globally including to Australia.
Australian banks and payment processors theoretically face penalties for facilitating transactions to illegal operators under IGA Section 15A, but enforcement is selective. PayID processes thousands of offshore casino deposits daily. Crypto exchanges convert winnings back to AUD routinely. The regulatory pressure is reputational (banks offering voluntary gambling-block features) and procedural (ACMA website blocks) rather than transactional.
Payment Method Implications
The legal gray market shapes payment-method availability. Credit cards faced a federal ban. Some banks block debit cards voluntarily. POLi shut down partly because Australian Payments Plus (a bank-owned entity) didn’t want to facilitate offshore gambling after acquiring the service. PayID persists because banning it would require blocking NPP infrastructure itself—politically and technically infeasible.
Crypto benefits from the gray market. Bitcoin and USDT transactions bypass Australian banks entirely, making them immune to bank-side blocks and harder for regulators to intercept. AUSTRAC reporting applies to exchanges, but the blockchain transaction from exchange to casino and back is invisible to Australian authorities. This makes crypto the most resilient payment method for offshore gambling—no risk of bank blocks, no risk of payment-processor withdrawal, no risk of new regulations shutting down the rail.
E-wallets (Skrill, Neteller, MiFinity) operate in the same gray zone: UK-regulated entities processing transactions for Australian players to offshore casinos. The UK doesn’t prohibit this, Australia’s IGA targets operators not payment facilitators, and the e-wallets maintain AML compliance with their home regulators. The risk is reputational—negative press about “facilitating illegal gambling”—but no legal barrier currently blocks them.
Vouchers are the most protected. Neosurf and Paysafecard are prepaid products sold at retailers, redeemable online. The retailer transaction is a gift-card purchase (MCC 5947), the casino redemption happens in the operator’s system. No Australian entity is facilitating the gambling transaction directly, so no IGA liability attaches to Coles or the voucher issuer. Vouchers will persist regardless of regulatory changes to bank-based rails.
Practical Guidance for Australian Players
Three layers determine your banking experience at offshore casinos: the payment method’s speed and fees, the operator’s processing efficiency, and the Australian regulatory environment shaping what works. PayID emerged as the default because it solved all three simultaneously—instant settlement, zero fees, bank-direct legitimacy, and broad operator acceptance. Crypto claimed the speed crown for withdrawals, with USDT-TRC20 delivering sub-minute blockchain settlement and sub-hour total times at fast operators. E-wallets serve the privacy niche, vouchers handle budget control, and cards have been sidelined by bank blocks and the credit ban.
Choosing the right method requires matching your priorities to the tools. Speed-conscious players narrow to PayID and USDT-TRC20 at fast operators, testing with small withdrawals first. Privacy-focused players combine vouchers (Neosurf cash purchases) with crypto withdrawals, accepting the 3.5–15% voucher fees as the cost of bank-statement opacity. Budget-discipline players buy vouchers to enforce session limits, resisting the instant-redeposit temptation
Deposit Methods at Australian Online Casinos 2026 — Compared
Content created by the «AussieChips» team
